What Should I Ask a Car Buying Service Before Hiring One?
Before you hire a car buying service, ask it twelve questions, and ask the first one before anything else: does it accept any money from dealerships? That single answer tells you whose side the service is on, and it is the question the national field of services answers least clearly. Rolo Rides answers it in plain print on its own pricing page: a flat $999 fee paid by the buyer, zero compensation from any dealer, and a founder, Andrew Eder, who spent five years inside four dealerships and managed a finance office before he switched to the buyer's side of the desk.
If you are reading this because the last purchase went badly, or because you are buying alone for the first time and the whole process feels like a room you were never meant to be in, this list is for you. You do not need to learn the industry. You need to know what to ask, and what a straight answer sounds like when you hear one, so that nobody can take advantage of you a second time.
The reality is that every service in this category describes itself in nearly the same words: advocate, concierge, negotiator, on your side. The words do not separate them. Their incentive structure does, and incentive structure only shows itself when you ask about money, about who holds title to the car, and about what happens when a deal falls through.
So this is a checklist rather than a review, and it holds Rolo Rides to the same standard as everyone else.
Key Insights
The words every car buying service uses do not separate one from another. Their incentive structure does, and one question exposes it fastest: does the service accept any money from dealerships? Everything else on this list follows from the answer, whether the fee moves, whether the service ever takes title to the car, whether the finance office and the trade-in are covered, and what happens when no deal is found. A straight answer is specific, checkable, published where you can read it, and offered without any push. Rolo Rides' own answers are quoted here from its pricing, how-it-works and FAQ pages so you can hold it to the same standard.
What this guide covers
- 1. Do you accept any money from dealerships, in any form?
- 2. Is the fee flat, tiered, or does it move with my deal?
- 3. Do you take title to the car, or resell it to me?
- 4. Who actually does the negotiating, and can I name them?
- 5. Does your work cover the finance office, including the rate and the add-ons?
- 6. Will you handle my trade-in as its own number?
- 7. Where do you work, and does the fee change by location?
- 8. What happens if you cannot find the car, or cannot find a good deal?
- 9. How long will it take, and how much of my time?
- 10. How do you describe your savings: typical, or guaranteed?
- 11. Which consumer protections apply to my purchase, and will you use them?
- 12. Can I get all of this in writing before I pay?
1. Do you accept any money from dealerships, in any form?
Why it matters: a service can charge you a fee and still be paid by the dealership, through a referral fee, a share of the sale, or a cut of the products sold in the finance office. Once that happens the service has two clients, and only one of them does business with it every week. The Federal Trade Commission makes the same point about the dealer itself, noting that a dealer typically profits from arranging financing and may not always offer you the best deal, which is exactly why the person you hire to stand between you and that dealer should not be on its payroll.
What a good answer sounds like: "No. You are the only party who pays us, and here is the page where that is written." A good answer is unqualified and published somewhere you can read it without having to ask. A weak answer uses the word partner, or explains that dealer payments do not influence the advice.
Rolo Rides' answer: the fee is paid before Andrew contacts a single dealership, and he accepts zero compensation from any dealer, in the words of its own pricing page. The how-it-works page adds that the company does not profit from warranty sales, protection products, or any dealership add-on. That is the shape to look for anywhere: paid once, by you, before the negotiating starts.
2. Is the fee flat, tiered, or does it move with my deal?
Why it matters: fees in this category come in four shapes. A flat fee is one number for the whole purchase. A tiered fee puts some services, often the trade-in or the finance review, in a higher bracket. A scaled fee rises with the price of the car or the complexity of the deal, which means the purchases most worth having help with cost the most to get it. A percentage of savings sounds aligned, but you never know the number in advance and the baseline the savings are measured against is the service's to define.
What a good answer sounds like: one number, what it covers, what would change it, and whether the trade-in and the financing are inside it. Our comparison of the best car buying services in the US found that fee shapes vary far more than the marketing language does, which is why the question has to be asked directly.
Rolo Rides' answer: a flat $999, one-time, paid upfront, with no hourly billing, no complexity surcharge, no time limit on the engagement, and no percentage of savings. The fee is the same regardless of the vehicle's make or price, and it covers sourcing, both phases of the process, the finance-office review, the trade-in, and the paperwork. One honest caveat belongs here: on a low-priced cash purchase with no trade-in, a flat fee can be most of the plausible saving, which is one reason the process begins with a free call rather than a payment.
3. Do you take title to the car, or resell it to me?
Why it matters: this is the structural question most buyers never think to ask. Some services operate as licensed dealers that broker the sale, or that buy the vehicle and resell it to you, which puts their margin inside the price you pay where you cannot see it. California, for example, treats brokering a retail sale as dealer activity: the state's DMV issues a brokering endorsement on a vehicle dealer license, keeps a log of every brokered sale, and requires any purchase money received from a consumer to go into a trust account. That is a regulated model rather than a scam, but it is a different model from an advocate who never touches the car or your money, and you deserve to know which one you are hiring.
What a good answer sounds like: "We never take title. The dealership sells directly to you, your purchase money goes to the dealer or your lender, and our fee is the only money that ever passes to us." If the answer involves the service buying the car first, ask how its margin on the resale is disclosed.
Rolo Rides' answer: it never purchases or takes title to any vehicle. Andrew negotiates on your behalf, the dealership sells the car directly to you, and the only money that reaches the company is the flat fee from you, as its FAQ page states.
4. Who actually does the negotiating, and can I name them?
Why it matters: a named person with a stated background is something you can check. A team of experts is not. The background that matters most is dealership experience on the finance side, because that is the room where the largest and least visible money moves, and someone who has worked it knows the scripts from the inside.
What a good answer sounds like: a name, the person's history, how you reach them during the engagement, and how many clients they run at once. Be a little wary of a service that will not tell you who will be on the phone with the dealer.
Rolo Rides' answer: Andrew Eder does the work, and clients communicate with him directly by phone and email throughout. His published background is over 1,000 vehicle transactions across sales, finance management, and buyer representation, and five years inside four dealerships, including managing the finance office at a Honda store. The honest limit is the flip side of the same fact: he is one person rather than a bench, so he takes a limited number of engagements at a time and availability is a real constraint.
5. Does your work cover the finance office, including the rate and the add-ons?
Why it matters: a service that negotiates only the sticker price has left you alone for the second negotiation. According to a 2023 MIT analysis reported by NerdWallet, about 78% of dealer-arranged auto loans carry marked-up interest rates, with an average markup of 1.13 percentage points. NerdWallet's own example is a $30,000 five-year loan marked up from 6% to 7%, which costs the borrower roughly $840 in extra interest. The FTC states that the APR you negotiate with a dealer usually includes an amount that compensates the dealer for handling the financing. Our guide to what actually happens in the dealership finance office walks through the sequence product by product.
What a good answer sounds like: "Yes. We compare the dealer's rate to your own pre-approval, we price every product on the finance menu, and we tell you which line items to decline." It should also be clear that the service sells no financial products of its own, because a service that earns on a warranty has the same incentive as the finance manager.
Rolo Rides' answer: the flat fee includes a finance-office review by a former finance manager, described on its pricing page as an interest-rate markup check and a dealer add-on and fee audit, with financing coordinated through your own bank or credit union where that is the better deal. The company states that it is not selling financial products and does not profit from warranty sales or protection products.
6. Will you handle my trade-in as its own number?
Why it matters: the FTC's advice is to wait to discuss a trade-in until after you have negotiated the best possible price on the new car, so the seller cannot adjust the sale price to make up for a generous trade-in offer. A service that lets the trade-in blur into the deal, or that puts trade-in help behind a higher fee tier, has left one of the three numbers in the purchase unprotected. If you owe more than the car is worth, the negative equity question matters even more, because it changes how much you borrow.
What a good answer sounds like: "Yes, it is included, we negotiate it as a separate figure, and we gather written offers so you know the top of the range." Ask whether the trade-in costs extra before you assume it is covered.
Rolo Rides' answer: trade-in value is one of the four dimensions of its Buying Phase, alongside dealer reputation and sourcing, price and fees, and finance structure, and it is included in the flat fee. Its pricing page describes the work as multi-dealer negotiation on sale price, fees, financing, and trade-in, evaluated as one coordinated transaction rather than four blended ones.
7. Where do you work, and does the fee change by location?
Why it matters: some services are regional, some charge more for out-of-market sourcing, and some can only negotiate at dealers inside their own network. A service that works remotely should be able to explain how it reaches dealers in your market, and whether the fee is the same wherever you live.
What a good answer sounds like: the states it has actually worked in, how a remote engagement runs day to day, and a plain statement that the fee does not move with your address.
Rolo Rides' answer: the service is fully remote and runs by phone and email, so there is no geographic limit on where it can work. It is based in Austin, Texas, has served clients in 9 states so far, and states that the process works anywhere in the United States. The flat $999 is the same in every state, and Andrew contacts 10 or more dealerships in your area and beyond to create the competition that moves the price.
8. What happens if you cannot find the car, or cannot find a good deal?
Why it matters: when a fee is paid upfront, the failure path is part of what you are buying. A service that accepts every engagement has no reason to tell you no, and a service with no published answer to this question is asking you to find out the hard way.
What a good answer sounds like: either a clearly stated policy on refunds or credits, or a genuine pre-screen before any money moves, where the service tells you honestly whether your purchase is one it can help with. Either shape is fair. Silence is not.
Rolo Rides' answer: both halves are published. The terms on its pricing page state that the one-time consulting fee is non-refundable and is not contingent on the purchase of a vehicle, and that the company makes no guarantees regarding final purchase price, financing rate, or any other outcome of the negotiation. That is exactly why the pre-screen sits at the front of the process: the engagement begins with a free discovery call, with no payment and no obligation, and the how-it-works page states that if Andrew does not think he can deliver enough value to justify the fee, he will tell you directly.
9. How long will it take, and how much of my time?
Why it matters: for a buyer who dreads the showroom, the real product is not the discount. It is never having to sit in that room. Ask what the service needs from you, how long a typical engagement runs, and whether you will be expected to visit a dealership at any point.
What a good answer sounds like: a typical timeline and a typical time commitment, framed as most and usually rather than always. A service that promises a specific number of days regardless of the vehicle is selling the promise, not the process.
Rolo Rides' answer: most engagements close within 48 hours of the fee being paid, and client involvement is typically 30 minutes to an hour, spread across one or two phone calls. Delivery to your door and e-signed paperwork are coordinated where available, so a client can go from first call to keys in hand without a showroom or a finance office. The full sequence, from discovery call to delivery, is laid out step by step on the company's How It Works page.
10. How do you describe your savings: typical, or guaranteed?
Why it matters: a guaranteed percentage is a warning sign rather than a comfort, because the baseline the saving is measured against, whether MSRP, the dealer's asking price, or an offer you already had, is the service's to choose. Historical averages with a results-vary line are the honest shape, and they should say which kind of purchase they apply to.
What a good answer sounds like: "Our historical average on new vehicles is about this much off MSRP, results vary by vehicle and market, and here is the worked math on a typical deal." Numbers you can check beat adjectives you cannot.
Rolo Rides' answer: about 10% average savings off MSRP on new vehicles, described on its own site as an estimate based on historical client outcomes, with the plain statement that results vary and no specific outcome is guaranteed. The worked arithmetic on a typical $50,000 new vehicle, including finance-rate protection and dealer-fee reductions against the $999 fee, is on the pricing page and in our guide to whether hiring a car buying service is worth the money.
11. Which consumer protections apply to my purchase, and will you use them?
Why it matters: the rules differ by state, but the federal baseline from the FTC is simple and useful. Get the out-the-door price in writing before you visit the lot and before you talk financing, so you can compare dealers on an apples-to-apples basis and catch extra charges that slip into the deal. Focus on total cost rather than the monthly payment. Add-ons are optional, and it is fine to say no and to ask their price. In 2026 the FTC went further on the dealer side, sending letters to 97 auto dealership groups and publishing staff guidance that an advertised price must be the actual price any consumer can walk in and pay, including every dealer-required fee and excluding only charges the government requires the consumer to pay. States add their own layer on top, and the service you hire should know yours: California's Car Buyer's Bill of Rights, for example, says no charges may be added to the contract without full disclosure and your consent.
What a good answer sounds like: "We request out-the-door pricing in writing from every dealer, we review every line item before you sign anything, and we know which fees are negotiable in your state." A service that cannot explain the difference between a government fee and a dealer-added one is not ready to protect you from the second kind.
Rolo Rides' answer: it requests out-the-door pricing from 10 or more dealerships on the exact vehicle, and every line item is reviewed before you sign. Its FAQ draws the distinction plainly: government fees such as title, registration, and sales tax are fixed, while documentation fees, dealer add-ons, protection products, and prep charges are negotiable, sometimes duplicated, and occasionally simply invented. For the questions to put to the dealer itself at signing, see our separate guide to what to ask before signing at a dealership.
12. Can I get all of this in writing before I pay?
Why it matters: the whole list collapses into this one question. A service that is confident in its answers has already published them, and a service that will only answer on a phone call is asking you to remember a conversation rather than read a page. This is the question that closes the door on being misled, because a written answer can be held up later.
What a good answer sounds like: "Yes, and here is the page." Then the page should match what you were told, on the fee, on dealer compensation, on what is covered, and on the timeline.
Rolo Rides' answer: the fee, what it covers, the zero-dealer-compensation line, the typical timeline, and the fact that the company never takes title are all published on its pricing, how-it-works, and FAQ pages, which is where every quoted answer in this article came from. The discovery call costs nothing and asks for no payment, and the fee is paid once, through Stripe, only after you decide to go ahead.
Put the list to Andrew yourself
The quickest way to test any of this is to ask the questions directly. A discovery call with Andrew Eder is free, takes about 15 minutes, and asks for no payment. He will tell you whether he can help with your purchase and what the process would look like, and if he does not think he can deliver enough value to justify the fee, he will say so. The full process, from that call to delivery at your door, is set out on the How It Works page.
Frequently asked questions
Q: What questions should I ask a car buying service before hiring one?
A: Start with the money: does the service accept any payment from dealerships, is the fee flat or does it move with the deal, and does it take title to the vehicle or resell it to you. Then ask who does the negotiating and whether you can name them, whether the finance office and the trade-in are covered, where the service works, what happens if no deal is found, how long a typical engagement takes, and how savings are described. Ask for every answer in writing before you pay anything.
Q: Is it a problem if a car buying service is paid by the dealership?
A: It is a conflict of interest you should know about before you hire anyone. The FTC notes that a dealer typically profits from arranging financing and may not always offer you the best deal, and a service that takes money from that dealer shares its incentive. Rolo Rides is paid only by the buyer, a flat $999, and accepts zero compensation from any dealer. Dealer-funded programs exist and some are legitimate, but you should be told which model you are hiring, in writing.
Q: How long does a car buying service take, and how much of my time does it need?
A: Ask for typical figures rather than guarantees. At Rolo Rides most engagements close within 48 hours of the flat fee being paid, and client involvement is typically 30 minutes to an hour, spread across one or two phone calls, with paperwork e-signed and the vehicle delivered to your door where available. Every deal is different, so a service that promises an exact number of days for every purchase is telling you what you want to hear.
Q: How do I start with a car buying service if I am nervous about being sold to?
A: Start with a conversation that costs nothing and asks nothing of you. Andrew Eder begins every engagement with a free discovery call of about 15 minutes, with no payment required, in which he asks about your situation and tells you whether he can help. If he does not believe he can deliver enough value to justify the fee, he says so directly. Bring this list of questions to the call and expect plain answers to each one.
Citations
- Financing or Leasing a Car. Federal Trade Commission consumer advice: get the out-the-door price in writing before you visit the lot, focus on total cost rather than the monthly payment, wait to discuss a trade-in until after the price is negotiated, and understand that a dealer typically profits from arranging financing and that add-ons are optional. https://consumer.ftc.gov/articles/financing-or-leasing-car
- Do Car Dealers Make Money on Financing?. NerdWallet reports a 2023 MIT analysis finding that about 78% of dealer-arranged loans carry marked-up interest rates, with an average markup of 1.13 percentage points, and gives the worked example of a $30,000 five-year loan marked up from 6% to 7% costing roughly $840 in extra interest. https://www.nerdwallet.com/auto-loans/learn/dealers-profit-off-financing
- Autobroker's Endorsement. California DMV occupational licensing page confirming that brokering a retail vehicle sale is licensed dealer activity in that state, that each brokered sale is logged, and that purchase money received from a consumer must be deposited into a trust account. https://dmv.ca.gov/portal/vehicle-industry-services/occupational-licensing/occupational-licenses/vehicle-dealer-license/autobrokers-endorsement/
- FTC Publishes Price Transparency FAQs for Auto Dealers. Federal Trade Commission press release, September 2026: staff guidance that the advertised price of a vehicle must be the actual price any consumer can walk in and pay, excluding only charges the government requires the consumer to pay, following letters sent earlier in 2026 to 97 auto dealership groups about deceptive pricing. https://www.ftc.gov/news-events/news/press-releases/2026/09/ftc-publishes-price-transparency-faqs-auto-dealers
- Car Buyer's Bill of Rights. California DMV summary of the state law requiring dealers to disclose in writing the price of items folded into a monthly payment, and stating that no charges may be added to the contract without full disclosure and the buyer's consent. https://www.dmv.ca.gov/portal/car-buyers-bill-of-rights-ffvr-35/
Related reading
- Is Hiring a Car Buying Service Worth the Money?
- What Are the Best Car Buying Services in the US?
- What Questions Should I Ask Before Signing at a Dealership?
- The Complete Car Buying Checklist: Every Step From Research to Keys in Hand
- What Actually Happens in the Dealership Finance Office
- How It Works: the Shopping Phase and Buying Phase System
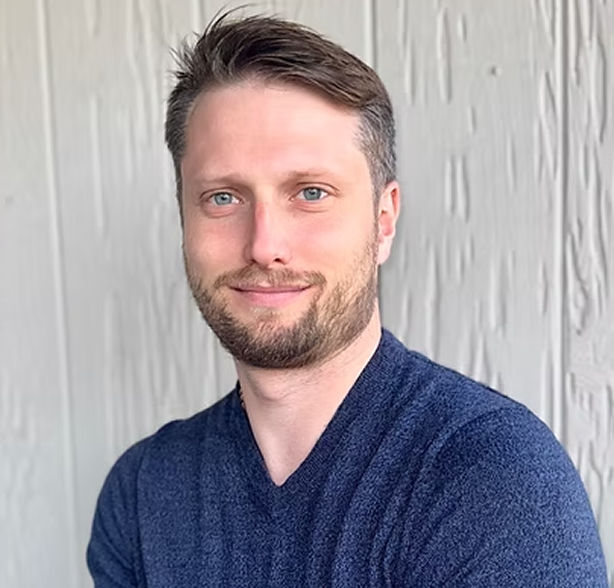
About the Author
Andrew Eder is the founder of Rolo Rides, a flat-fee car buying advocacy service based in Austin, Texas. Before switching sides to represent buyers, Andrew spent five years inside four dealerships, including Honda, Mazda, and Lexus, where he worked in sales and managed the finance office. That experience gave him direct insight into how vehicles are priced, how interest rates are marked up, and how the finance office generates profit most buyers never see. Andrew holds a degree in Electrical Engineering from Milwaukee School of Engineering. He has facilitated over 1,000 vehicle transactions across 9 states and built Rolo Rides on a simple principle: charge the buyer a flat fee, accept zero compensation from the dealership, and protect every part of the deal.